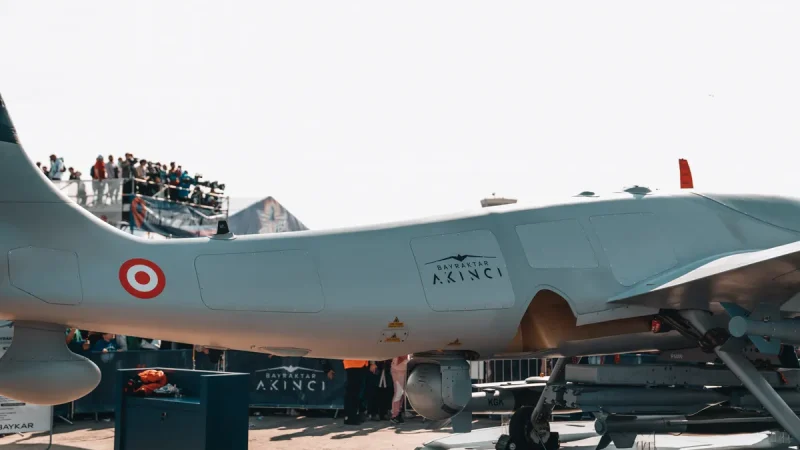
Vector and Nammo Armed Drones Scale Up for Mass Production
Vector Defense and Nammo announced an expanded partnership Monday at the Association of the United States Army’s annual...
Red Cat Holdings has released its most significant quarterly results to date, presenting a financial picture marked by both staggering growth and deepening challenges. The company’s latest earnings report reveals a historic surge in sales paired with a substantial increase in net losses, creating a complex narrative for market participants.
The fourth quarter of fiscal 2025 saw Red Cat achieve a monumental revenue milestone. Sales skyrocketed to $26.2 million, representing an increase of 1,985% compared to the $1.3 million reported in the same period last year. This performance met the high end of the company’s own forecast, underscoring a significant operational ramp-up. For the full fiscal year, revenue grew by 161%, supported by a 520% expansion in production capacity.
However, this top-line explosion was accompanied by a net loss of $72.1 million. The company maintains a solid liquidity position of $167.9 million, bolstered by extensive capital-raising activities. CEO Jeff Thompson characterized 2025 as a “transformative year,” highlighting the deepened collaboration with the U.S. Army and a first-time order for 100 Black Widow drones from NATO’s procurement agency, NSPA, as evidence of growing international demand.
A primary focus for investors and analysts ahead of the earnings call was the company’s financial outlook for 2026. Management’s response was brief and definitive: “We will not be providing guidance today.” This decision leaves a critical question unanswered: the projected timeline for the company’s path toward profitability.
Despite this, analyst sentiment remains largely optimistic. Ladenburg Thalmann raised its price target from $15 to $20, citing Red Cat’s scaling potential. Needham & Company reaffirmed a buy rating with a $16 target. The consensus price target, derived from 14 ratings, stands at $19.33. A note of caution comes from Weiss Ratings, which maintains a sell recommendation based on the stock’s negative price-to-earnings ratio and high volatility.
Red Cat shares currently trade at €14.75, having more than doubled since the start of the year. A Relative Strength Index (RSI) reading near 95 indicates the stock is in deeply overbought territory. Based on its forward price-to-sales ratio, the company trades at a discount to comparable defense drone competitors. Yet, without concrete multi-year guidance, any further re-rating of the stock is contingent upon clear deliverables: visible new contract wins and measurable margin improvement. While management has promised progress on both fronts in 2026, it has provided no specific numerical targets.
Vector Defense and Nammo announced an expanded partnership Monday at the Association of the United States Army’s annual...
The TSMC earnings season preview is the week’s focal point, with Taiwan Semiconductor Manufacturing (TSMC) reporting Thursday as...
The EU-China hybrid deal announced on October 9 in Beijing is less a resolution than a redirect: Brussels...