State Dept Clears Path for F-35 Saudi Arabia Sale Worth $24.3 Billion
The US Department of State has approved a potential F-35 Saudi Arabia sale worth an estimated $24.3 billion,...
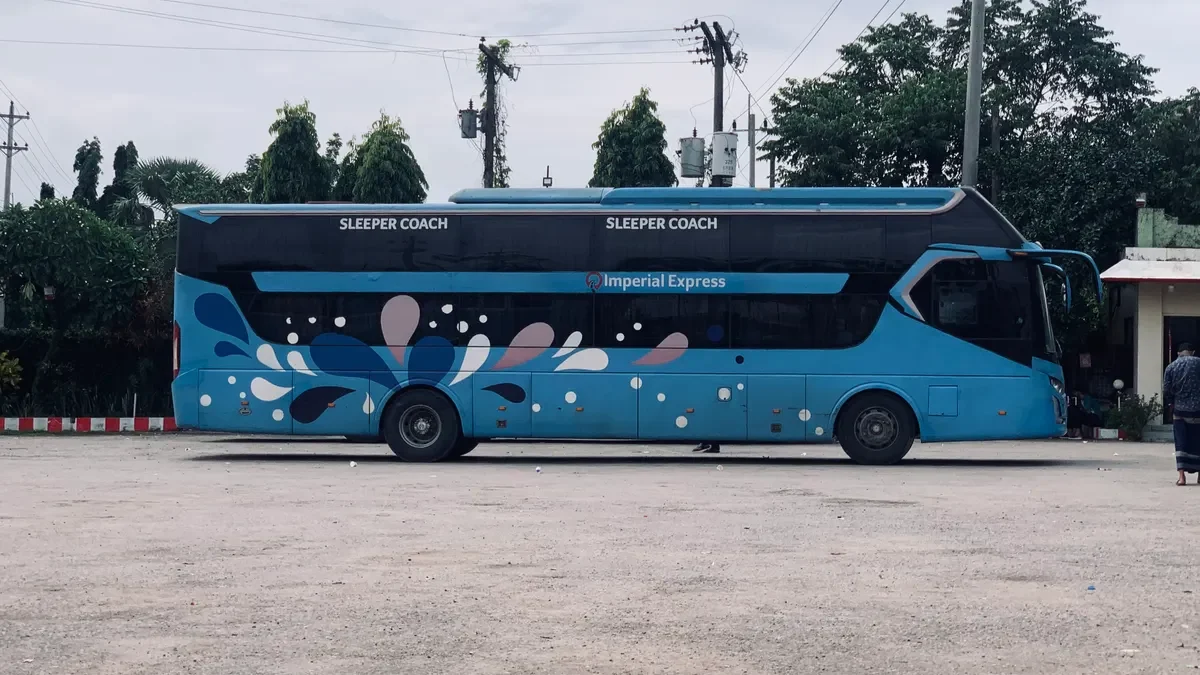
Marcopolo’s return to the European coach market is less a product launch and more a strategic pivot, one driven by a softening home market and an export revenue line that is growing fast enough to reshape the Brazilian bus maker’s business mix. The vehicle is the Volvo B13R chassis paired with the Marcopolo Paradiso G8 body, set to debut at the Feria Internacional del Autobús y del Autocar (FIAA) in Madrid next week, with first orders already placed in France, Italy, and Portugal.
The context matters. Reuters reported that Marcopolo’s domestic revenue fell 10% year-on-year in 2025 to 4.95 billion reais ($943.94 million), with the Brazilian market expected to come in slightly below even that level in 2026 as persistently high interest rates delay fleet renewals. The Selic rate stood at a near-two-decade high of 15% before Brazil’s central bank trimmed it by 25 basis points to 14.75%, and that modest cut has not been enough to unlock the domestic cycle.
The export response is visible in the numbers. International operations accounted for 45.4% of Marcopolo’s total net revenue in 2025, up from 36.3% the year before, according to Automotive World. Europe is the logical next leg of that diversification, and the Volvo partnership provides a faster route than building dealer and aftersales networks from scratch.
The commercial arrangement is structured to reflect Marcopolo’s limited European footprint. Volvo Buses will hold full commercial and aftersales responsibility in Italy and France; in Spain and Portugal the two companies share it, with additional European markets described as potentially to follow. That split is sensible: it gives Marcopolo distribution reach and Volvo’s aftersales infrastructure without requiring Marcopolo to staff up across the continent.
The geographic scope has also widened since the deal was first disclosed. An October 2025 Volvo Buses press release announced the partnership with scope limited to France and Italy only. The September 2026 announcement adds Spain and Portugal, suggesting early commercial traction was sufficient to justify broadening the arrangement before the first coach has even been delivered.
Thomas Nylund, Volvo Buses’ Head of Europe, framed the value proposition clearly: “Together, we can now offer a premium coach that combines Volvo’s renowned chassis technology, fuel efficiency, and safety with Marcopolo’s modern design, comfort, and coach-building expertise. This partnership gives us greater flexibility to meet the diverse needs of our customers.”
The coach is offered in 4×2 and 6×2 axle configurations, targeting long-distance and tourism operators. Customer deliveries are expected to start in early 2027, meaning the first real commercial test of European demand will land roughly a year from now.
Marcopolo’s 2025 annual management report noted that certification of coaches for the European market was in progress, which explains why this partnership is only now converting into confirmed orders rather than earlier. European type-approval requirements are demanding, and piggybacking on Volvo’s established Swedish-made B13R chassis shortens that certification path considerably.
The bull case is straightforward: Europe becomes a meaningful third pillar alongside Brazil and Marcopolo’s other international operations (which include the Australian subsidiary Volgren and a Canadian affiliate), giving the company a high-margin, developed-market revenue base that offsets domestic cyclicality. The bear case is execution risk. First orders in France, Italy, and Portugal are encouraging, but converting a debut product into a recurring European order book takes years of aftersales performance and competitive pricing against established European coachbuilders.
The read here is that Marcopolo needed this deal more than Volvo did, and that reality is priced into the commercial structure: Volvo holds the customer relationship in the two largest initial markets. For investors in Marcopolo, the question is whether the European revenue contribution can scale quickly enough to offset the Brazil drag. The early-2027 delivery date is the first concrete checkpoint to watch.
The US Department of State has approved a potential F-35 Saudi Arabia sale worth an estimated $24.3 billion,...
The Air Force supply hole runs $14 billion deep, and the officers responsible for keeping the service’s aircraft...
The Porsche-cylib battery recycling pilot has crossed a threshold that separates proof-of-concept from something operationally serious: battery cathode...