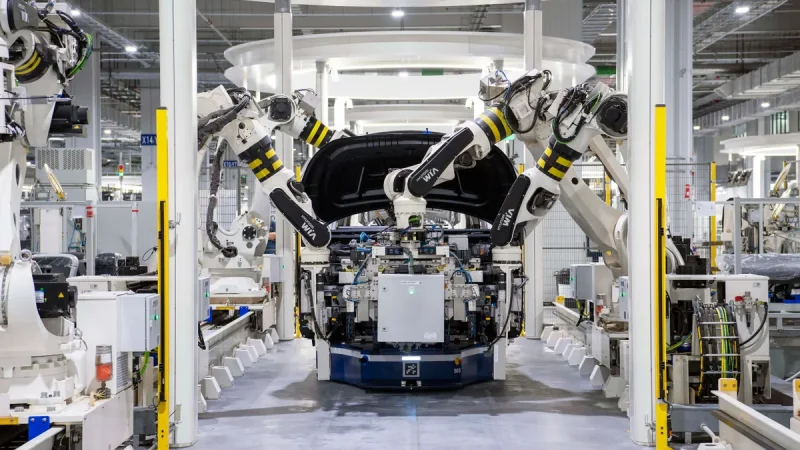
Volvo Cars EBIT Margin Push Rests on Geely Synergies and a 13-Model Bet
The Volvo Cars EBIT margin target of above 8% is an ambitious number for a company that reported...
Salesforce (CRM) set a fiscal 2030 revenue target of over $63 billion at its Dreamforce investor session, clearing every major analyst consensus by a margin that forces a reassessment of how aggressively the company is leaning into AI-driven growth. The question is whether the number reflects genuine momentum or, as at least one skeptic argues, a reprise of a long-range target Salesforce has already missed before.
Three polling firms, three different baselines: analysts surveyed by LSEG had pegged fiscal 2030 revenue at $59.2 billion, those tracked by the Wall Street Journal via FactSet expected $60.66 billion, and the Bloomberg consensus sat at $61.4 billion. Against all three, the $63 billion-plus figure represents a beat of between $1.6 billion and $3.8 billion.
Bloomberg notes the target includes revenue from Salesforce’s acquisition of Informatica, completed last November. A prior $60 billion long-range target had excluded that deal, per a Yahoo Finance report on the earlier Dreamforce investor day. The organic ask, then, is more demanding than the headline gap between old and new targets implies.
That organic demand is where Guggenheim plants its flag of concern. The firm maintained a Neutral rating after Dreamforce, noting the $63 billion target requires a 10%-plus organic revenue CAGR from fiscal 2026 to 2030, against a current growth rate of 8.33%, according to Investing.com. The firm also cited Salesforce’s prior $50 billion-plus target for fiscal 2026 as a cautionary precedent. It is the most pointed institutional pushback on the guidance.
Bulls counter with the Data and AI segment, which reached $1.2 billion in revenue in the second quarter, up 120% year over year. BofA Securities, which kept a Buy rating with a $325 price target, cited the company’s greater-than-10% CAGR topline growth goal alongside a “rule of 50” margin target implying significant operating leverage. Canaccord Genuity (Buy, $300) and Wolfe Research (Outperform, $310) both maintained constructive ratings after the event.
Alongside the revenue target, the Anthropic investment is reshaping how investors read Salesforce’s balance sheet. The company’s 10-Q filed with the SEC for the fiscal quarter ended July 31, 2026 shows unrealized gains on the Anthropic stake of $2.7 billion for that quarter alone, and $3.0 billion for the six months ended July 31, 2026. (Earlier reporting references a $2.6 billion gain on strategic investments; the 10-Q’s $2.7 billion figure, drawn from the primary filing, is the more precise measure of the quarterly unrealized movement.)
Salesforce’s strategic investment portfolio now spans more than 450 companies with a combined carrying value of $11.3 billion, according to Yahoo Finance citing the quarterly filing. The Anthropic position alone carries a value of approximately $5.1 billion, making it by far the largest single holding. That stake began with roughly $50 million in early 2023, per a Bloomberg report from June 2026.
CEO Marc Benioff told the Dreamforce gathering that Salesforce will “probably” sell the Anthropic position, using the proceeds to pay down debt tied to the company’s accelerated share repurchase program. That program, announced March 11, 2026, totals $25 billion and is half of a $50 billion board-authorized buyback plan, funded by a $25 billion senior notes offering, according to Investing.com. Cumulative repurchases have now reached $60 billion.
The stock jumped nearly 23% after the latest earnings report, its best single-session performance since 2020, lifted by those unrealized investment gains and better-than-expected operating results. Up to 1,000 clients have signed up for the beta of Claudeforce, the product integrating Salesforce data with Anthropic’s Claude, and Slack has re-emerged as a hub for AI agent communication.
The case for the bull thesis rests on three reinforcing pillars: a Data and AI segment growing triple digits, an Anthropic stake that has compounded from $50 million to roughly $5 billion and could fund further buybacks, and Dreamforce signaling enough enterprise demand to justify the acceleration in organic growth required to hit $63 billion. The bear case, in Guggenheim’s framing, is that Salesforce has made a long-range revenue promise before and missed, and that the acceleration from 8.33% to 10%-plus organic growth is not yet visible in the current run rate. The evidence leans constructive for patient holders, but the burden of proof is on the next several quarters of organic revenue execution, not on a target set four years out.
The Volvo Cars EBIT margin target of above 8% is an ambitious number for a company that reported...
Germany’s Patriot interceptor deal moved into new territory Tuesday when German Defense Minister Boris Pistorius and U.S. Defense...
The Tesla Cybercab NHTSA probe crossed a legal threshold this week: the regulator has issued a formal Special...