Operation Epic Fury Purple Hearts: Three Soldiers Acted Under Fire to Save Lives
Three U.S. Army soldiers received Purple Hearts for their actions during the Operation Epic Fury Purple Hearts ceremony...
As AMETEK prepares to release its next set of financial results, its stock is demonstrating notable strength, trading close to an all-time peak. This sustained upward momentum is underpinned by a history of robust quarterly performance and favorable adjustments from market analysts.
The company’s recent fundamental results provide a solid foundation for investor confidence. In its most recent quarter, AMETEK posted record revenue of $1.89 billion, marking a year-over-year increase of 10.8%. Earnings per share came in at $1.89, significantly surpassing the consensus estimate of $1.76.
The equity has consistently outperformed the broader S&P 500 index over the past twelve months, delivering gains of approximately 18%. Currently, the share price trades well above key moving averages, notably the 50-day average of $200.86 and the 200-day average of $190.23.
Market researchers have recently refreshed their ratings on the industrial technology firm, reaffirming a broadly optimistic outlook. The consensus rating for AMETEK stands at “Moderate Buy.” This breakdown shows ten analysts recommending “Buy,” three advising “Hold,” and one issuing a “Strong Buy” recommendation.
The average 12-month price target has been revised upward to $223.75, suggesting a potential upside of around 5.7% from current levels. Several institutions have raised their targets:
* Barclays increased its target from $205.00 to $210.00.
* Keybanc lifted its price objective from $220.00 to $235.00.
* Mizuho adjusted its target higher, from $225.00 to $230.00.
Market participants are now looking ahead to the publication of AMETEK’s fourth-quarter 2025 results. Company guidance projects earnings per share for the closing quarter to be in the range of $1.90 to $1.95. For the full 2025 fiscal year, management anticipates EPS between $7.32 and $7.37.
This projected growth is largely driven by the performance of the Electromechanical Group, which recently reported double-digit order growth. The aerospace and defense segments, contributing nearly 20% of total revenue, continue to see high single-digit growth rates. A solid book-to-bill ratio of 1.00x indicates sustained demand for the company’s offerings.
Three U.S. Army soldiers received Purple Hearts for their actions during the Operation Epic Fury Purple Hearts ceremony...
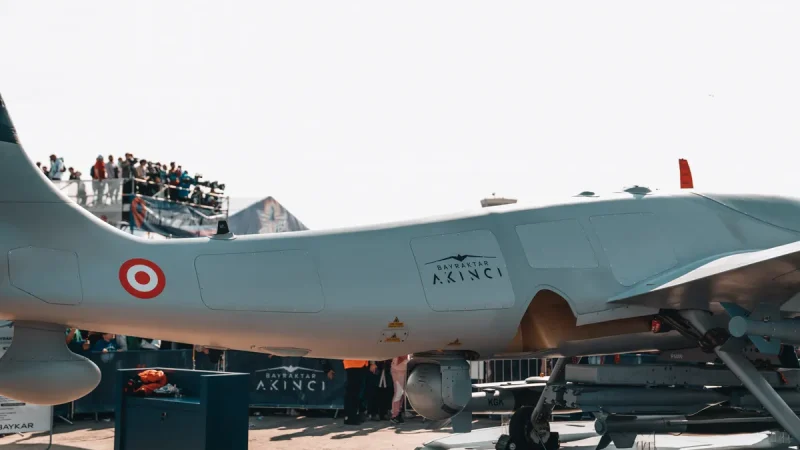
Vector Defense and Nammo announced an expanded partnership Monday at the Association of the United States Army’s annual...
The TSMC earnings season preview is the week’s focal point, with Taiwan Semiconductor Manufacturing (TSMC) reporting Thursday as...