Nvidia, Micron, and the Jobs Report That Moved Markets
Three forces drove last week’s market action: a softer-than-expected jobs report that lifted rate-hold odds, a record-breaking Micron...
European defense startup funding is on track for a record $10.5 billion this year, according to Dealroom, and the numbers make clear this is a structural shift rather than a temporary spending spike. The story is not just volume; it is concentration, geography, and the emergence of a cluster that is beginning to rival Silicon Valley’s defense-tech ambitions.
Germany is the top European country for defense venture capital this year, with $3.5 billion raised, ahead of Finland at $1.2 billion, the U.K. at $932 million, and France at $376 million, per Dealroom. That represents a reversal from 2025, when the U.K. led Europe with $2.9 billion raised versus Germany’s $2.1 billion, according to a Dealroom and NATO Innovation Fund report published in February 2026.
Munich is the engine of that German dominance. The city attracted $3 billion in venture capital as of September 20, per Dealroom, ahead of Helsinki, London, Berlin, Cambridge, and Paris. Dealroom called Munich “the powerhouse of the European defense tech ecosystem,” pointing to Helsing and Quantum Systems as the anchor companies: together they carry a combined valuation of $25.7 billion.
Helsing’s July fundraise tells you why. The company closed a $1.8 billion Series E round on July 13, 2026, which valued it at approximately $18 billion, up from a reported €12 billion valuation in June 2025, according to Defense News. Investor demand significantly exceeded the available allocation, and the company said it remains predominantly European-owned after the fundraise, with its board unchanged: Daniel Ek and Tom Enders as co-chairmen, alongside former NATO Supreme Allied Commander Transformation Gen. Denis Mercier and the three co-founders.
Quantum Systems followed on July 2 with a $1.2 billion Series D round that valued the company at approximately $8 billion post-money, according to the company’s official press release. The round was co-led by Blackstone, Noteus, Airbus, and Advent, with Fidelity, Wellington Management, and A.P. Moller Holding among participants. Co-CEO Florian Seibel told CNBC that the company is profitable, and the capital will go toward production capacity, supply chain resilience, and AI development.
Mega rounds, defined by Dealroom as the very largest raises, accounted for more than 85% of European defense venture capital invested this year. The concentration of that money into drones and autonomous systems is the defining sectoral bet. Drones and autonomous systems drew 74% of EU defense VC and 77% of U.K. defense VC, compared to 57% in the United States.
Within Europe, unmanned aerial vehicles led with $4.7 billion raised as of September, followed by Earth observation and satellite imagery at $1.8 billion, anti-drone solutions and launch vehicles at $1.2 billion each, and maritime robotics at $796 million. Ground robotics is the clear laggard, with only $77.6 million raised so far this year.
That gap matters for investors thinking about portfolio completeness. Air and space are scaling fast; ground autonomy is still in formation. Germany and the Netherlands each allocated over 15% of their national venture capital to defense, security, and resilience companies in 2025, per the Dealroom and NATO Innovation Fund February 2026 report, suggesting the pipeline behind these mega-rounds is not empty.
The NATO-wide picture adds context. Defense startups across NATO countries have already raised $27.1 billion in venture capital so far in 2026, more than the $14.5 billion raised across all of 2025, with Dealroom forecasting a $38.5 billion total by December. Including private equity, debt, and grants, total private investment in NATO defense startups is forecast to reach $42.7 billion, up from $16.9 billion a year earlier.
Dealroom is direct about what is driving Europe specifically: “This is Europe catching up rather than the U.S. slowing. EU 27 funding more than doubled in a year.” Defense now accounts for 15% of overall venture capital funding in the EU, up from 6.2% a year earlier. It is the fastest-growing sector in European startup funding, ahead of space and robotics.
The bull case is that the Munich cluster has produced two anchor companies with real government contracts, real revenue (Quantum Systems is profitable), and enough institutional backing to survive a market correction. The bear case is that mega-round concentration cuts both ways: 85% of capital flowing through a handful of deals means a stumble by Helsing or Quantum Systems would drag the headline numbers sharply lower. For NATO allies and the private investors backing them, the near-term test is whether the cohort forming in ground robotics, counter-drone, and hypersonics can follow the Munich giants into profitability before the geopolitical urgency that is funding all of this begins to fade.
Three forces drove last week’s market action: a softer-than-expected jobs report that lifted rate-hold odds, a record-breaking Micron...
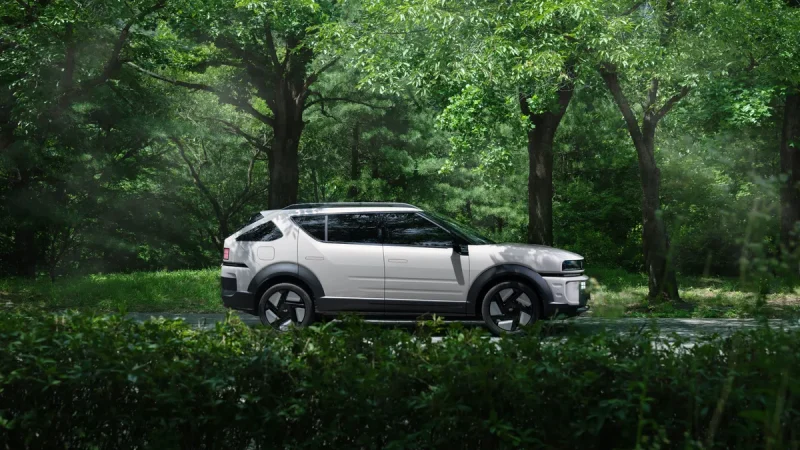
Rivian R2 deliveries reached a record 19,248 vehicles in Q3 2026, up 46% year-over-year and ahead of analyst...
Accenture’s (ACN) earnings beat in fiscal Q4 2026 was not a mild outperformance: it was the company’s strongest...