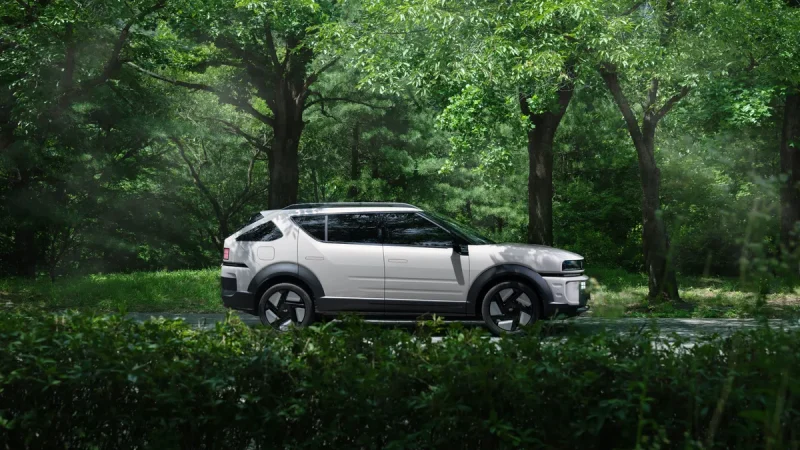
Rivian R2 Deliveries Beat Estimates, But Losses Frame the Real Test
Rivian R2 deliveries reached a record 19,248 vehicles in Q3 2026, up 46% year-over-year and ahead of analyst...
Three forces drove last week’s market action: a softer-than-expected jobs report that lifted rate-hold odds, a record-breaking Micron (MU) quarter, and Nvidia’s (NVDA) historic $150 billion share repurchase authorization. Taken together, they sketch a market that is leaning on AI-driven earnings momentum and easier monetary conditions to sustain its advance.
September’s nonfarm payrolls came in at 29,000, well short of the Dow Jones consensus of 84,000, while the unemployment rate ticked up to 4.2% against a 4.1% forecast. On its face, that is a weak number. The market read it as a gift.
Soft payrolls, combined with a cooler-than-expected August PCE print earlier in the week, pushed the probability of the Federal Reserve holding rates steady at its late October meeting to 78%, up from 36% the prior week, according to the CME FedWatch Tool. Lower near-term rate pressure relieves one of the few macro overhangs on large-cap tech, where valuations remain stretched. Oil prices also pulled back Friday on reports that European nations are considering releasing strategic fuel reserves, removing a second headwind.
The Nasdaq climbed 1.2% on Friday, briefly touching an intraday all-time high. The S&P 500 gained 0.7% and the Dow added 0.5%.
Micron’s fiscal fourth-quarter 2026 results were the headline event for semiconductor investors. Revenue of $54.23 billion surged 379% year over year, and adjusted EPS of $33.42 beat expectations. According to Micron’s Q4 fiscal 2026 prepared remarks, this was the company’s sixth consecutive quarterly revenue record, with full-year fiscal 2026 revenue reaching $133.2 billion, up 256% year over year, per Micron’s SEC-filed earnings press release.
The underlying composition of that revenue matters. DRAM accounted for $39.8 billion of Q4 revenue, a 343% year-over-year increase representing 73% of total quarterly sales, according to Investing.com’s earnings call transcript. GAAP gross margin hit 86.8% in Q4, up from 84.6% sequentially, and operating cash flow reached $43.97 billion for the quarter, per Micron’s investor relations press release.
Forward guidance was equally strong. Micron guided for $61.5 billion in revenue and $38.15 in adjusted EPS for the first quarter of fiscal 2027, both above Wall Street estimates. Management expects supply-demand conditions to be tighter in 2027 and 2028 than in 2026, with roughly 75% of its expected 2027 output already under commitment. The company also disclosed 26 strategic customer agreements, up from 16 last quarter.
Shares still ended the week down 0.7%. Investors are weighing whether expanded manufacturing investment eventually floods the market with supply and compresses margins. That concern is not unreasonable, but the demand visibility embedded in those customer agreements and the output pre-commitment rate make a near-term price collapse harder to argue. A CHIPS Act funding restriction easing expected in December could also unlock a significant buyback, adding a capital return catalyst that the stock currently lacks.
Nvidia’s $150 billion repurchase authorization increase, which the company’s board described as the largest such increase in history, brings the total remaining authorization to $235 billion, with execution targeted through fiscal year 2028, according to the NVIDIA Investor Relations press release. Jensen Huang framed the move as a natural extension of the company’s cash generation: ‘NVIDIA’s growth is being driven by a once-in-a-generation platform shift to AI and accelerated computing. Our cash generation gives us the capacity to invest in the technologies that advance this transformation and return capital to shareholders.’
The cash generation backing that claim is substantial. In the first half of fiscal 2027 through July 2026, Nvidia produced $69.9 billion in free cash flow on $74.42 billion in operating cash flow, according to The Globe and Mail. In Q2 alone, the company returned approximately $26 billion to shareholders, including $19.7 billion in buybacks and $6 billion in dividends. Buyback pace has accelerated sharply: approximately $34 billion in fiscal year 2025, over $40.4 billion in fiscal year 2026, and already $39 billion through the first half of fiscal 2027, per Yahoo Finance. According to The Motley Fool, Nvidia returned 60% of free cash flow through buybacks and dividends in the first half of fiscal 2027, against a long-term target of at least 50%.
The bull read here is straightforward: Nvidia shares are up roughly 24% this year but rank among the weaker performers in the iShares Semiconductor ETF even as adjusted EPS has more than doubled in back-to-back quarters. A $235 billion authorization gives management the firepower to compress the share count meaningfully, directly accelerating per-share earnings growth. Wall Street expects roughly $440 billion in free cash flow over the next six quarters, making the authorization credible rather than aspirational.
Nvidia gained 3.95% on the week and punched through its May intraday all-time high on Friday, though it fell short of a record close. The $235 billion authorization is the test: if Nvidia deploys capital at the pace it demonstrated in the first half of fiscal 2027, the disconnect between business performance and stock performance should close. The risk is that AI infrastructure spending by hyperscalers plateaus sooner than the consensus expects, cutting into both revenue and the free cash flow that funds the buyback.
Rivian R2 deliveries reached a record 19,248 vehicles in Q3 2026, up 46% year-over-year and ahead of analyst...
Accenture’s (ACN) earnings beat in fiscal Q4 2026 was not a mild outperformance: it was the company’s strongest...
The BMW Neue Klasse battery plant at Irlbach-Straßkirchen, Bavaria, has entered series production ahead of its original timeline,...