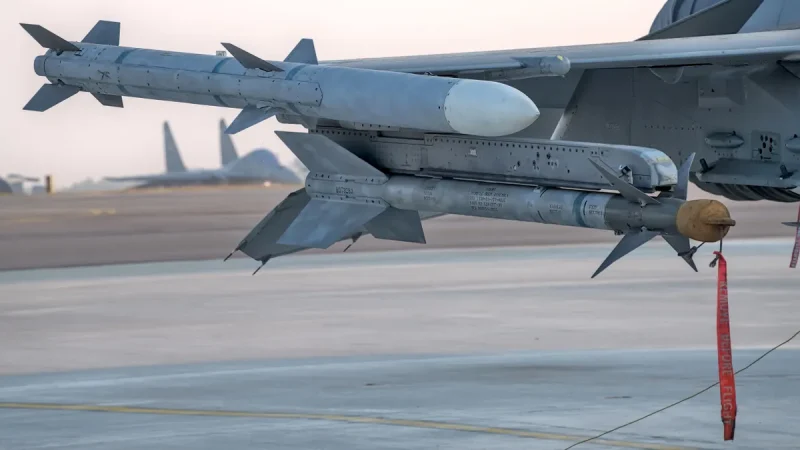
Raytheon’s $20.7B AMRAAM Contract Is a Bet on Arsenal of Freedom
Raytheon’s AMRAAM contract with the Pentagon, worth up to $20.7 billion over five years, is the largest single...
The Pentagon’s $450 million investment in Elmet Technologies (ELMT) is less a routine defense contract than a structural bet: Washington has decided it cannot leave the tungsten supply chain in Beijing’s hands any longer, and Elmet is the only US-owned entity capable of anchoring it.
The investment is structured as redeemable preferred equity, with an initial $200 million drawdown at closing and additional tranches to follow. According to the Elmet press release, the Department of War will also receive warrants representing up to 19.9% of ELMT’s common stock on a post-transaction basis, plus the right to appoint one independent board member. That is a meaningful equity stake, and it signals the government intends to stay closely involved with how this capital is deployed.
The investment was executed by the Department of War’s Office of the Assistant Secretary for Industrial Base Policy in partnership with the Economic Defense Unit, funded through the Industrial Base Analysis and Sustainment program.
China controls roughly 85% of the global tungsten supply and about 40% of molybdenum, a closely related material. The US has not mined tungsten since 2015. A federal procurement rule barring tungsten mined, refined, or processed in China, Russia, Iran, and North Korea from defense applications takes effect January 1, which creates a hard deadline that compresses Elmet’s execution timeline considerably.
Critical-minerals analyst Chris Berry put the price dynamic plainly on his podcast: the rise in tungsten prices is “due almost exclusively to policy choices in Beijing and Washington.” Berry said the combination of Chinese export controls and US procurement restrictions has created “two distinct markets” and that “the free flow of tungsten material is for now a thing of the past.” The metal’s demand is small in absolute terms but highly price-inelastic, which means supply constraints translate quickly into cost pressure for defense manufacturers.
The metal’s properties explain why substitution is not viable at scale. Tungsten carries the highest melting point of any metal and is approximately as dense as gold. Combined with carbon, it forms tungsten carbide, used across industrial tooling and military munitions. Berry called it “a must-have” for the defense sector and noted it is also used in semiconductor fabrication for AI data centers. “There’s no good substitute at scale for most of these applications,” he said.
The Department of War’s investment will fund the construction of the only independent ammonium paratungstate (APT) facility in North America, according to the official release. APT is a critical intermediate in tungsten processing and, per that release, represents one of the largest chokepoints across the US industrial base. Getting refining capacity onshore addresses the weakness Berry flagged: “Every mined dollar should be paired with a processing dollar.”
Elmet’s disclosed capital allocation breaks down as $165 million for upgrading domestic manufacturing in Maine, Michigan, and Ohio; approximately $150 million to restart mining operations in Imlay, Nevada; and $100 million to establish a refining and trading division. Those three items total $415 million; the remaining allocation is not itemized in the company’s press release.
Elmet currently operates nearly 400 employees across three facilities totaling more than 500,000 square feet, according to the company’s manufacturing overview. The Ohio and Michigan plants came through its 2023 acquisition of H.C. Starck Solutions Americas. The company went public earlier this year, with its S-1 registration statement declared effective by the SEC on April 22, 2026, per reporting by StockTitan citing ELMT SEC filings.
Beyond the Nevada restart, StockTitan’s reporting on ELMT SEC filings also references a planned investment of approximately $125 million in Masan High-Tech Materials and a joint investment of $150 million to $175 million with Blue Moon and EQ Resources into the Springer Tungsten Complex in Nevada to expand paratungstate conversion capacity. These figures go beyond what the company’s own press release itemizes and should be treated as preliminary.
Elmet already supports more than 100 defense programs, including Patriot, Javelin, AEGIS, Trident II, THAAD, and Virginia- and Columbia-class submarines. International supply partnerships with Tungsten West in England and Vietnam’s Masan High-Tech Materials Corporation are intended to spread risk across allied suppliers.
The investment thesis here rests on execution. Elmet is the right vehicle: it is the only US-owned fully integrated tungsten producer, its customer base is locked in, and the regulatory deadline creates immediate demand pull. The risk is the same as for any industrial ramp: capital is committed, but converting it into permitted, operational mines and processing facilities on schedule is the hard part. If the Nevada restart slips or the APT facility faces permitting delays, the supply gap the government is trying to close stays open. Watch the first production milestones from Imlay; those will tell investors whether the timeline is real.
Raytheon’s AMRAAM contract with the Pentagon, worth up to $20.7 billion over five years, is the largest single...
BYD’s second-generation Seagull, revealed through Ministry of Industry and Information Technology (MIIT) filings, is a fundamentally different car...
Nissan’s 80% US production target, disclosed at a media roundtable in Yokohama on September 28, is less a...