Pentagon Locks In a $450M Elmet Tungsten Supply Chain Deal
The Pentagon’s $450 million investment in Elmet Technologies (ELMT) is less a routine defense contract than a structural...
Ashok Leyland‘s production forecast, as modeled by Automotive World, shows total output peaking at roughly 222,000 units in 2026/27 before a two-year contraction takes volumes to around 202,000 in 2028/29, then a recovery to a fresh cyclical high of approximately 242,000 units by 2031. The read here is that AL’s record fiscal year 2025/26 is not the top of a durable upcycle: a truck-led downturn is coming, the bus segment will cushion it, and the LCV division is the structural growth story investors should watch.
AL delivered 220,437 trucks, buses, and light commercial vehicles in 2025/26, a new all-time peak and an 11.7% rise from the prior record set in 2018/19. On a consolidated basis, revenue grew 14% to INR 515 billion (approximately US$5.4 billion), the highest in the company’s history and the fourth consecutive year of top-line growth.
The commercial vehicle division did the heavy lifting. CV revenue rose 13.6% to INR 443 billion, and operating profit climbed 19.5% to INR 53.3 billion, lifting the operating margin by 0.6 percentage points to 12.0%. That margin expansion came despite higher input costs across raw steel, aluminum, copper, and rubber, offset partly by improved unit revenues and procurement restructuring.
Export momentum was a secondary driver. Full-year export volumes climbed 18.5% to 18,082 units, raising the international sales mix to 8.2% of total deliveries from 7.8% the prior year and 6.2% at the 2018/19 peak.
The Ashok Leyland production forecast through 2031 reflects three divergent segment trajectories. Automotive World projects MHCV truck output at approximately 106,700 units in 2026/27 before falling 11-12% the following year and bottoming around 91,200 units in 2028/29. The reasoning traces to demand indicators that have turned negative: spot freight rates on key routes are under pressure, operator profitability has weakened, dispatches from major industrial hubs have fallen, and fuel costs have risen. India’s central bank, the Reserve Bank of India, is widely expected to raise interest rates at its October meeting, adding a financing headwind on top of the operating pressure.
The GST rate reduction that took effect in October 2025 delivered a demand surge, but that boost now creates a tough base-effect comparison for the second half of 2026/27. Automotive World expects total industry volumes in that period to fall below year-ago levels as the stimulus pull-forward fades.
Bus production is a different picture. State transport undertaking electrification tenders and a fixed 15-year legal age limit for government buses, in effect since April 2023, underpin a more regulated demand curve. AL’s bus output is forecast to continue rising to a cyclical peak in 2027/28 before a relatively mild two-year correction.
LCV is where the structural opportunity sits. AL targets a 25% domestic market share, against roughly 20% currently, and plans to get there by launching new models including the Saathi mini-truck and a new 4-6 tonne entry planned for 2027/28. LCV deliveries already hit a record 77,779 units in 2025/26, up 12.6%, and Automotive World forecasts the segment reaching approximately 88,900 units by 2031.
The early read on the current fiscal year confirms both the volume strength and the cost pressure the Ashok Leyland production forecast is built around. According to the company’s Q1 FY2026-27 press release, AL posted record Q1 commercial vehicle volume of 48,763 units, up from 44,238 units in the prior-year Q1, alongside record Q1 revenue of INR 9,634 crore.
Profitability, however, compressed. Per Investing.com’s earnings summary, PAT rose just 3% to INR 609 crore while EBITDA margin fell to 10.1% from 11.1% a year earlier, as material costs climbed 90 basis points to 71.5% of revenue. Management responded with cumulative price increases of 2.25% in MHCV and 3.5% in LCV to claw back the input inflation. The company’s net cash position stood at INR 2,252 crore at the quarter’s close.
Within the Q1 volumes, domestic MHCV deliveries rose 15% and domestic LCV deliveries rose 21%, both setting Q1 records. Defense revenue surged 64% and power solutions revenue rose 51%, underscoring that AL’s earnings base is broader than its headline truck cycle.
The bull case rests on management’s expectation that commodity costs will peak in Q2 before easing in the second half of the fiscal year, restoring margins as pricing gains take hold. The LCV share-gain story and a growing electric mobility order book provide growth vectors that are less correlated to the MHCV freight cycle.
The bear case is straightforward: if freight rates and operator economics deteriorate faster than forecast, the truck downturn could be sharper than the 11-12% projected for 2027/28, and price hikes in a weakening demand environment risk losing share rather than defending margin.
The production forecast for Ashok Leyland ultimately hinges on one variable: how long the Indian freight cycle takes to trough. A faster recovery in highway freight volumes would pull the 2031 peak closer; a prolonged softening would push it out. The margin trajectory in the current fiscal second half is the first real read on which scenario is playing out.
The Pentagon’s $450 million investment in Elmet Technologies (ELMT) is less a routine defense contract than a structural...
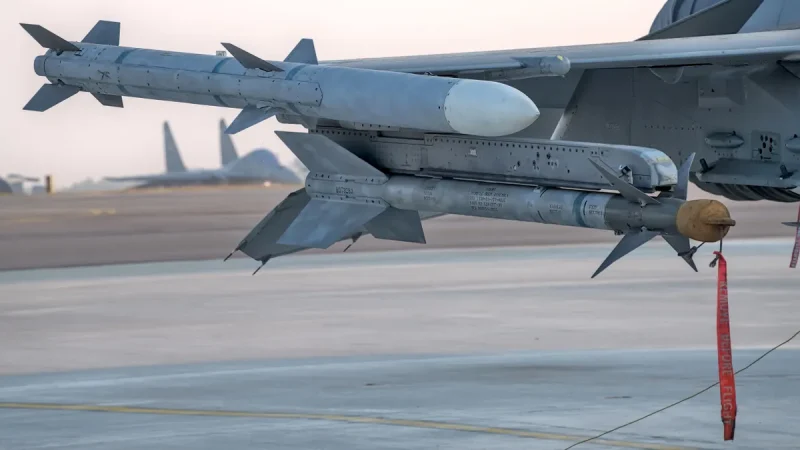
Raytheon’s AMRAAM contract with the Pentagon, worth up to $20.7 billion over five years, is the largest single...
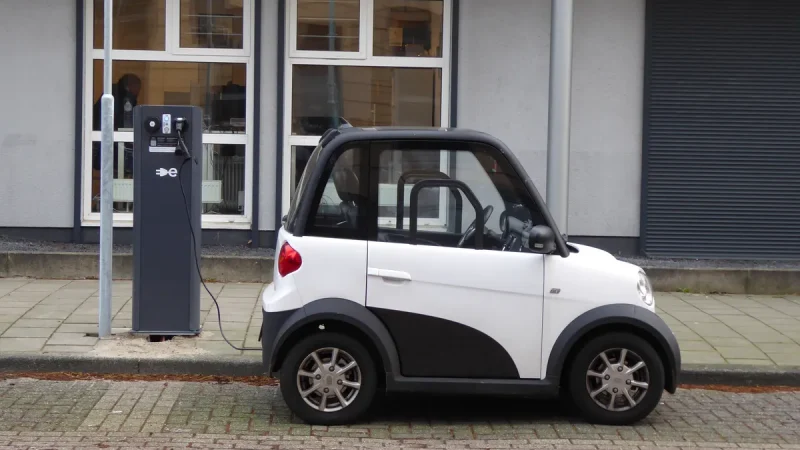
BYD’s second-generation Seagull, revealed through Ministry of Industry and Information Technology (MIIT) filings, is a fundamentally different car...