Honda Ohio Hybrid Plant Bets Up to $2.5bn on Flex-Line Future
The Honda Ohio hybrid plant in development, reported by Nikkei on September 24, is not simply a capacity...
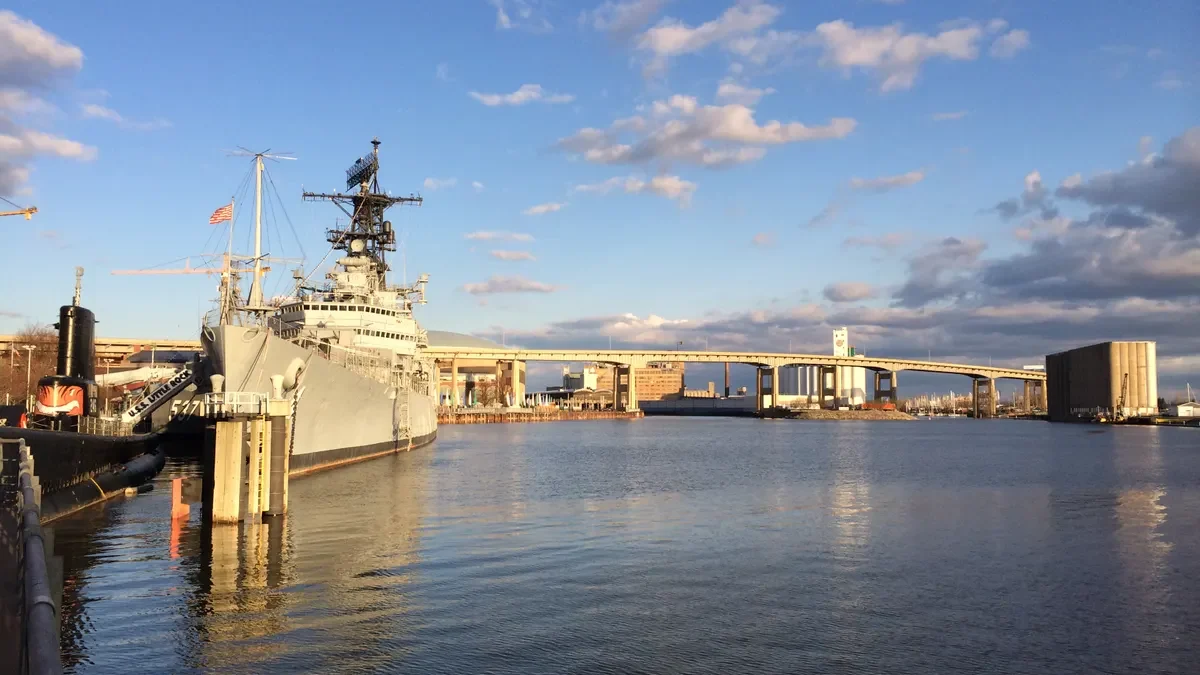
The Italy DDX destroyer contract, signed through European procurement office OCCAR, commits €3.7 billion ($4.2 billion) to build two next-generation warships for the Italian navy, with deliveries scheduled for 2033 and 2035. The headline figure looks clean, but the structure underneath it matters: roughly €1.3 billion of the total consists of options, per Reuters, leaving the firm commitment closer to €2.4 billion. That distinction separates a guaranteed revenue base from contingent upside.
The contract was signed with Orizzonte Sistemi Navali (OSN), a joint venture in which Fincantieri holds 51% and Leonardo holds the remaining 49%. OSN is expected to cement sub-supply contracts with each partner in the coming weeks, according to Breaking Defense: approximately €1.8 billion to Fincantieri and approximately €1.7 billion to Leonardo, per a joint company statement cited by Reuters. The split is nearly even despite Fincantieri’s majority ownership of OSN, which reflects how central Leonardo’s combat systems are to the program’s total value.
For Fincantieri, the DDX is platform engineering at scale. Each destroyer displaces 13,500 tonnes, runs 180 meters in length, carries a crew of 251, and is rated for a range of 4,000 nautical miles. At 15 knots, the vessel can manage unmanned assets, including underwater and surface drones, through an integrated digital backbone developed by Fincantieri, Naval News reports, citing a Fincantieri press release. That drone-management capability is a meaningful differentiator from the Horizon-class vessels the DDX will ultimately replace.
For Leonardo, the value proposition is the combat system. The DDX will carry Leonardo’s SADOC 5 command-and-control system, a digital S-band AESA radar, and MBDA weapon systems. Beyond the hardware, Leonardo’s official press release states that the DDX combat system delivers an integrated air and missile defense (IAMD) capability against missile, ballistic, and hypersonic threats, and that a next-generation electronic warfare suite completes the package. The architecture also underpins Leonardo’s “Michelangelo project,” which targets full multi-domain interoperability, a capability framework that positions the DDX program as a template for future export pitches, not just a domestic fleet renewal.
Leonardo CEO Lorenzo Mariani said the new vessels will allow the Italian Navy to “rely on naval platforms offering advanced operational performance and capable of addressing a broad spectrum of threats.”
The DDX order sits at the end of a sustained Italian naval build-out that has already included FREMM-class frigates, PPA multimission ships, a new landing helicopter dock, new submarines, and logistics vessels. The DDX ships will initially sail alongside, and eventually replace, the Italian navy’s two existing Horizon vessels, according to a navy spokesman cited by Defense News. That replacement timeline gives both Fincantieri and Leonardo a long program runway, but it also means the revenue profile stretches well into the 2030s.
The options structure is where investors should focus. The €1.3 billion options tranche is real potential revenue, but it is not booked until exercised. If Italy’s defense budget holds and the program stays on schedule, those options convert to firm orders. If procurement priorities shift (or if early milestones slip) the exercisable portion shrinks. Neither Fincantieri nor Leonardo has disclosed what conditions govern option exercise.
The bull case is straightforward: Italy is spending at a scale that generates multi-year revenue visibility for both companies, and the DDX’s IAMD and multi-domain architecture positions OSN for follow-on export business as NATO allies modernize surface fleets. The bear case is the options overhang and the long delivery window. Revenue from 2033 and 2035 deliveries will not move near-term earnings, and the approximately €2.4 billion in firm commitments, divided across two delivery years and two companies, represents a revenue contribution that is meaningful but not transformative for either Fincantieri’s or Leonardo’s current scale.
The key test is option conversion. If Italy exercises the €1.3 billion options tranche in a defined timeframe, the DDX becomes a substantially larger program than the firm commitment alone implies. Until then, the contract is best read as a long-duration, moderate-certainty revenue anchor for both companies, with the combat-system architecture offering Leonardo the more defensible competitive moat.
The Honda Ohio hybrid plant in development, reported by Nikkei on September 24, is not simply a capacity...
The Renault Clio Green NCAP result of 62% and three and a half stars, achieved with a conventional...
Toyoda Gosei’s India expansion takes its most direct form yet in Maharashtra: a new plant in Bidkin built...