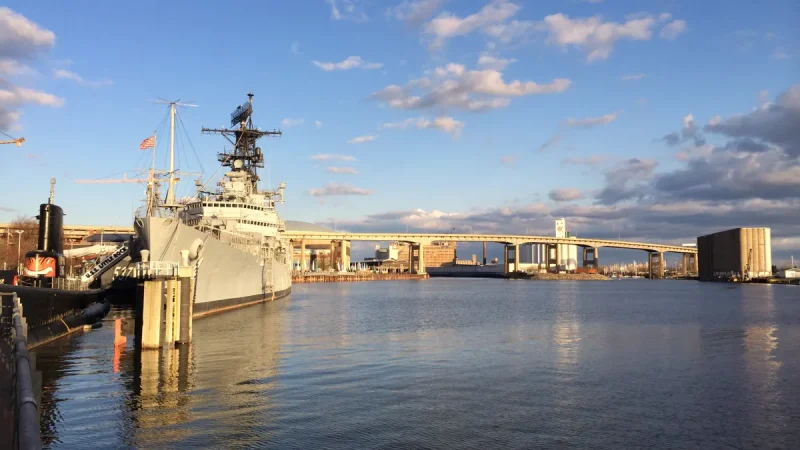
Italy DDX Destroyer Contract Locks In €3.7bn for Fincantieri and Leonardo
The Italy DDX destroyer contract, signed through European procurement office OCCAR, commits €3.7 billion ($4.2 billion) to build...
Costco Wholesale (COST) reported fiscal fourth-quarter results Thursday that showed Costco membership renewal rates moving in the right direction, but not decisively enough to settle the debate about whether the warehouse retailer’s growth engine is stalling. The result: a price target cut to $1,050 from $1,100, with the hold-equivalent 2 rating held in place.
Total revenue for the 16-week August quarter rose 11.1% year over year to $95.72 billion, topping the $94.86 billion Wall Street consensus compiled by LSEG. Adjusted earnings per share climbed 15% to $6.75, also ahead of estimates, and still beat consensus even after stripping out a 15-cent benefit from tariff refunds, which came after the Supreme Court ruled in February that President Trump’s emergency levies were unconstitutional.
For the full fiscal year ended August 30, 2026, Costco Wholesale reported net sales of $297.247 billion, up 10.1% from $269.912 billion in fiscal 2025, with total revenue reaching $303.154 billion. Fourth-quarter net income came in at $2.998 billion, up 14.9% from the prior-year period, and full-year operating income rose to $11.685 billion from $10.383 billion.
The balance sheet also strengthened. Cash and cash equivalents stood at $20.207 billion as of August 30, 2026, up from $14.161 billion a year earlier, supported by $15.825 billion in operating cash flow for the fiscal year.
Membership fee income in the quarter grew 7.3% to $1.85 billion, a sliver below the FactSet estimate of $1.86 billion. For the full fiscal year, membership fee income totaled $5.907 billion, up from $5.323 billion in fiscal 2025, per Costco’s earnings press release.
The sequential trend in renewal rates is where the bull-bear argument lives. The worldwide renewal rate edged to 89.8% from 89.7%, a level that had been flat for three prior quarters. The U.S. and Canada rate ticked to 92.3% from 92.2%. Small moves, but the direction matters given that renewal rates had been under pressure from a rising share of online sign-ups, which churn at a higher rate than in-store registrations. Costco’s own SEC 10-Q filing for the period ended May 10, 2026 flagged that dynamic explicitly.
The catch is that paid members of 84.1 million missed expectations and grew only 3.8% year over year. That extends a deceleration that ran 4.1%, 4.8%, and 5.2% across the prior three quarters of fiscal 2026. A year earlier, Costco’s fiscal 2025 annual filing showed total paid members at 81.0 million, with executive members at 38.7 million. The latest quarter puts executive members at 42.3 million, an all-time high. Executive members pay $130 per year versus $65 for the basic tier and renew at a higher rate, so the mix shift is a structural positive.
CEO Ron Vachris said on the earnings call, “Renewal rates showed improvements again this quarter, with the increasing executive penetration likely to help improve those rates in the future.”
The bull case rests on a few pillars. Comparable sales rose 9.4% in the quarter, above the 9% FactSet estimate, with traffic up 3.3% and ticket size up 5.9%. Digital comparable sales jumped 19.5%. The under-40 member base has grown nearly 60% since Covid and now represents more than a quarter of the total membership. Younger members eventually grow into higher spenders, and CFO Gary Millerchip noted on the call that “AI continues to grow in its influence on how our members are searching for products,” with site traffic from AI search up triple digits for the second consecutive quarter at the highest conversion rate of any channel.
The bear case is valuation compression. Shares closed Thursday’s regular session at $896.48, down 18% from the May 19 high. The gross margin contracted 11 basis points year over year to 11.02% (though it expanded 20 basis points excluding the impact of gas price inflation). With membership growth decelerating for four straight quarters, the premium multiple that Costco historically commands needs follow-through on renewals and executive mix before it can be re-rated upward.
On capex, Costco plans to spend $7.5 billion in fiscal 2027, up from $6.4 billion in the just-concluded fiscal 2026, targeting 28 new warehouse openings plus five relocations. The company currently operates 939 locations worldwide. Per earnings call highlights reported by Yahoo Finance, tariff refunds received in Q4 were used to reduce prices on produce, meat, beverages, and home goods, with a similar refund already received in the first quarter of fiscal 2027 and earmarked largely for member value reinvestment.
The evidence leans modestly constructive: two positive data points on renewal rates, an all-time high in executive members, and a clean comp beat. But one quarter of sequential improvement is not a trend. The multiple will not re-expand until the paid membership growth rate stops declining, and that requires at least another quarter of data. The $1,050 price target reflects a stock that has done enough to hold, but not enough to buy.
The Italy DDX destroyer contract, signed through European procurement office OCCAR, commits €3.7 billion ($4.2 billion) to build...
The Honda Ohio hybrid plant in development, reported by Nikkei on September 24, is not simply a capacity...
The Renault Clio Green NCAP result of 62% and three and a half stars, achieved with a conventional...